
Table of Contents
- It's PSMC, Not TSMC: Why the Partner Name Changes the Whole Story
- What Tata's Dholera Fab Actually Is: The Hard Numbers
- 90nm First, 28nm Later: The Node Roadmap Nobody Announced Loudly
- From Agreement to Mid-2028: How the Dholera Timeline Actually Moved
- The $2 Billion Debt Raise and the ASML Tool Deal
- Why Tata's Dholera Fab Matters for South Asia's Chip Supply
- Frequently Asked Questions
- Is Tata's Dholera fab a TSMC plant?
- Who is PSMC and what does it actually make?
- How much does the Dholera fab cost and who is paying?
- When will the Dholera fab start commercial production?
- Will Dholera make smartphone or AI chips?
- Does the Dholera fab affect chip prices in Pakistan?
- What is the difference between the Dholera fab and the Assam OSAT plant?
- What Could Still Go Wrong — And What the Alternatives Are
- The Bottom Line
- References
- Related Reading
It’s PSMC, not TSMC. Tata’s Dholera fab is being built with Powerchip Semiconductor Manufacturing Corporation, a Taiwanese specialist in mature nodes, not with TSMC. The project carries a ₹91,000 crore (about $11 billion) investment and is designed for 50,000 wafer starts per month on 300mm wafers across nodes from 28nm to 110nm. Production starts on 90nm and 55nm. India’s Technology Minister Ashwini Vaishnaw has placed commercial operations in mid-2028, not 2026.
Headlines, social posts and even some trade write-ups have quietly folded Tata’s Gujarat project into the TSMC story, as though India had somehow landed the world’s leading-edge foundry. It is PSMC, not TSMC — Tata Electronics is building the Dholera fab with Powerchip Semiconductor Manufacturing Corporation (PSMC) of Taiwan, not with TSMC — and the difference determines what chips India will actually be able to make. The distinction is not pedantry. Because PSMC sells mature-node capability while TSMC sells bleeding-edge logic, confusing the two produces wildly wrong expectations about whether Dholera will ever print a flagship smartphone processor. This piece sets out the verified specifications, the revised timeline, the November 2026 funding round and the ASML tool deal, then explains the practical consequence for buyers and manufacturers across South Asia. For more hardware and supply-chain reporting, see The Verge PK technology coverage.
About this analysis: Written by the technology desk at The Verge PK homepage, which covers device availability, telecom, fintech and manufacturing policy for readers in Pakistan and South Asia.
Transparency note: This article is an assessment of publicly available company statements, government releases and news reporting current as of November 14, 2026. It is not an engineering audit of the facility, and none of the figures here were independently verified on site.
It’s PSMC, Not TSMC: Why the Partner Name Changes the Whole Story
Tata Electronics’ manufacturing partner at Dholera is PSMC — Powerchip Semiconductor Manufacturing Corporation — a Taiwanese foundry that specialises in mature process nodes and memory, not TSMC. Both companies are Taiwanese, which is the likeliest root of the confusion, and both operate 300mm fabs. There the similarity ends. Under the partnership, PSMC supplies fab design, construction support and engineering technology transfer, according to Tata Electronics’ own project disclosures covering the Dholera facility.
The consequence of the correction is commercial, not cosmetic. TSMC’s value sits in 3nm and 2nm logic for smartphone systems-on-chip and AI accelerators, so a TSMC-anchored fab would have signalled India entering the bleeding edge directly. PSMC’s business is the workhorse end of the market — TrendForce’s foundry capacity analysis places it among the mature-node and memory specialists rather than the leading-edge group — which means Dholera is aimed at power management ICs, display drivers and microcontrollers rather than flagship processors. It also means the process recipes arriving in Gujarat are licensed, not owned. As USPTO guidance on technology transfer in manufacturing partnerships describes, a licensee works inside the scope of the transferred process IP, and that scope constrains how quickly a new fab can climb the node ladder regardless of how fast it builds. Readers tracking the broader question of licensed versus open standards in technology supply chains will recognise the lock-in tradeoff.
Framed properly, the choice reads as deliberate rather than second-best. Mature nodes carry lower capital risk per wafer and a much shorter learning curve for a workforce being assembled from scratch. Therefore PSMC is the partner that makes a first fab actually finishable.
| Dimension | PSMC (Powerchip) | TSMC |
|---|---|---|
| Core process nodes | Mature nodes, roughly 28nm and above | Leading edge, including 3nm and 2nm |
| Primary product focus | Memory and mature-node foundry services | Advanced logic for smartphones and AI accelerators |
| Role in the Dholera project | Fab design, construction support, engineering technology transfer | No announced role |
| Typical end markets | Power management, display drivers, MCUs, industrial | Flagship mobile SoCs, high-end computing, AI silicon |
What Tata’s Dholera Fab Actually Is: The Hard Numbers
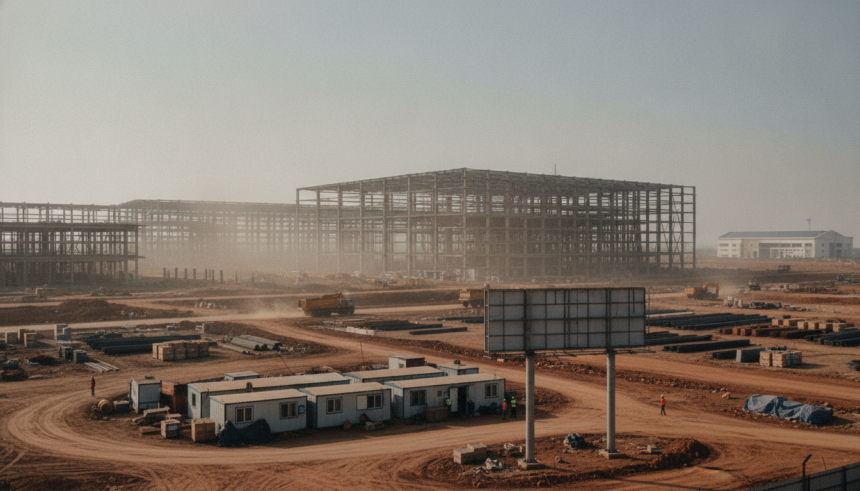
Tata’s Dholera fab is a ₹91,000 crore (about $11 billion) greenfield 300mm foundry in Dholera, Gujarat, designed for 50,000 wafer starts per month across process nodes from 28nm to 110nm. The funding structure matters as much as the headline number: the Indian government is providing 50% fiscal support on a pari-passu basis under a Fiscal Support Agreement signed in March 2025, as recorded in Press Information Bureau releases on India’s semiconductor mission. Pari-passu means state money moves in step with Tata’s own spending rather than arriving as a lump sum, which means Tata’s effective exposure is roughly half the headline figure and the project’s cash-flow economics depend on disbursement keeping pace with construction milestones.
The facility is described as a pure-play commercial foundry, a phrase that appears in press releases far more often than it is explained. It means Dholera manufactures other companies’ chip designs to order rather than Tata-branded products. Consequently its success is measured by customer qualification wins — the point at which a fabless designer certifies that parts coming off the Dholera line meet specification — rather than by Tata’s own product sales. It is also positioned as an AI-enabled fab, a label that refers to automated process control and data-driven yield management of the kind now standard in automated and AI-enabled manufacturing pipelines.
Capacity needs calibration. At 50,000 WSPM on mature nodes, Dholera is a mid-sized facility by Taiwanese or Korean standards, yet it represents effectively all of India’s commercial wafer capacity built from a standing start. That asymmetry is exactly why Tata’s ₹27,000 crore OSAT plant in Assam matters as the downstream half of the pair, because wafer output alone does not produce a sellable chip.
| Specification | Figure |
|---|---|
| Total investment | ₹91,000 crore (approx. $11 billion) |
| Government fiscal support share | 50%, pari-passu, under March 2025 FSA |
| Monthly wafer capacity | 50,000 wafer starts per month |
| Wafer diameter | 300mm (12-inch) |
| Process node range | 28nm to 110nm |
| Nodes at production start | 90nm and 55nm, with 28nm phased in |
| Expected commercial operations | Mid-2028 |
| Projected direct and indirect jobs | Over 20,000 |
90nm First, 28nm Later: The Node Roadmap Nobody Announced Loudly
Early communication around the project foregrounded 28nm, but reports in mid-2026 confirmed Dholera will begin production on 90nm and 55nm processes and introduce 28nm gradually. PSMC spokesperson Eric Tang clarified the roadmap in July 2026, stating that technology transfers are typically introduced in stages beginning with mature nodes — standard practice for a new facility rather than a retreat from the original plan.
The engineering cause is straightforward. Yield learning on a new fab is driven by process control, tool matching and operator competence, none of which exist on day one. Starting at a more forgiving node reduces scrapped wafers and gives engineers room to build discipline before the tolerance budget tightens at 28nm, where defect sensitivity and overlay accuracy demands rise sharply. Attempting the tightest available node first would therefore raise cost per good die at precisely the moment the fab can least afford it.
For customers, the consequence is better than it sounds. 90nm and 55nm are exactly where power management ICs, display drivers and automotive microcontrollers live, which means Dholera’s opening product mix is commercially real rather than a trial run.
What Dholera’s Opening Nodes Are Actually Good For
- Power management ICs for phones, chargers, inverters and solar equipment
- Display driver ICs for televisions, monitors and automotive clusters
- Microcontrollers for appliances, two-wheelers and industrial control
- Analogue and mixed-signal parts for IoT and metering
- Logic for automotive and consumer electronics that does not need sub-10nm density
From Agreement to Mid-2028: How the Dholera Timeline Actually Moved
India’s Technology Minister Ashwini Vaishnaw has indicated commercial operations at Dholera are now expected to begin in mid-2028, revised from an earlier late-2026 target. The chronology below tracks how the project moved from a signed agreement to an active construction site with a longer runway.
Dholera Fab Timeline
- March 2025 — Fiscal Support Agreement signed, committing 50% government support on a pari-passu basis
- Through 2025 — Site development and construction at Dholera, Gujarat, moves from groundwork toward cleanroom build
- May 2026 — Tata Electronics announces a lithography tool supply and talent-development partnership with ASML
- July 2026 — Node roadmap clarified: production to begin on 90nm and 55nm, with 28nm phased in
- End of 2026 — First test chips targeted
- November 2026 — Tata Electronics opens talks to raise up to $2 billion in bank debt
- Mid-2028 — Commercial operations expected, per India’s Technology Minister
The slip is structural rather than managerial. A greenfield fab requires ultrapure water at semiconductor grade, uninterrupted power, cleanroom certification, tool installation and qualification, and a trained workforce that did not previously exist in India at this scale. As NIST’s semiconductor metrology and CHIPS R&D programmes document, measurement capability and process control qualification are themselves multi-quarter undertakings that follow tool install rather than running alongside it. Therefore the schedule is set by the slowest dependency in that chain, not by how quickly concrete and steel go up.
This is why the test-chip milestone — first test wafers targeted around the end of 2026 — is the honest indicator to watch. Test chips demonstrate that the tool chain runs end to end and that material actually moves through the line, which means they necessarily precede any credible commercial production claim. A fab that has not produced test silicon cannot be close to qualifying customer parts.
The $2 Billion Debt Raise and the ASML Tool Deal
As of November 2026, Tata Electronics is in early discussions with domestic and international banks to raise up to $2 billion across multiple loan tranches, with a first tranche of up to $800 million priced around SOFR plus 180 basis points, as reported by The Economic Times. The pricing is the signal worth reading. SOFR plus 180 basis points is lender pricing for a credible sponsor rather than a distressed one, which means banks are underwriting Tata’s balance sheet and the government support agreement rather than the fab’s unproven yield. Lenders are backing the sponsor, not the silicon — a distinction that matters if ramp-up disappoints.
The equipment side was settled earlier. In May 2026 Tata Electronics announced a partnership with Dutch lithography maker ASML covering supply of essential lithography tools plus local talent development and research support, per ASML’s own announcement. No fab operates without a lithography vendor relationship, because lithography sets the achievable node and the vendor’s field engineers keep the tools inside specification. Therefore securing ASML removes the single largest equipment risk and simultaneously imports training capacity India currently lacks in depth.
5 Critical AI Governance Challenges in Multi-Institution Research Labs – theverge.pk
The remaining constraint is the one Tata Sons chairman N Chandrasekaran flagged himself at the Bloomberg New Economy Forum in October 2026, when he stressed monitoring the energy requirements of infrastructure at this scale. Fabs consume power and ultrapure water continuously, and an interruption mid-process scraps wafers already in the line. Utility reliability at Dholera is consequently a commercial variable that lands directly in cost per wafer, not an infrastructure footnote.
Why Tata’s Dholera Fab Matters for South Asia’s Chip Supply
Tata’s Dholera fab matters for South Asia’s chip supply because it localises mature-node production of the power management ICs, display drivers and microcontrollers the region currently imports almost entirely from Taiwan, South Korea and China. South Asia’s electronics and automotive assembly lines run on those imported parts. Therefore any East Asian supply shock, shipping disruption or export-control action reprices the entire region’s bill of materials within a quarter, and assemblers have no domestic fallback to switch to.
The ecosystem effect compounds the capacity effect. Dholera is paired with Tata’s ₹27,000 crore OSAT facility in Assam, which handles assembly and test. Because fabricated wafers are commercially useless until they are diced, packaged and tested, the two plants together create a front-to-back domestic value chain rather than one isolated plant with an export dependency for packaging. That pairing is also what makes the mature-node output relevant to the broader hardware story our AI hardware and compute coverage tracks, since accelerator boards and data-centre power stages consume large volumes of mature-node analogue parts alongside leading-edge logic.
Precision matters here for readers in Pakistan and elsewhere in the region. Indian capacity is not automatically regional capacity, because trade policy, tariffs and bilateral restrictions determine whether Pakistani importers ever see a price effect. The realistic channel is indirect: a larger regional mature-node supply base softens global pricing for the commodity parts inside chargers, inverters, televisions and electricity meters, and it builds a South Asian engineering talent pool that recruiters across the region draw from. Chandrasekaran’s October 2026 framing — “We are in a beautiful spot in India, because we have the talent, we have the domestic market, we can play a part in every global supply chain” — is the strategic argument for why that talent base forms at all. The cost of failure is equally concrete: if Dholera misses mid-2028, the region’s import dependency simply persists for another product cycle.
What Changes for the Region if Dholera Delivers
- Mature-node parts for automotive and appliances sourced within the region instead of only from East Asia
- A packaging and test route through Assam, closing the gap between wafer output and finished chips
- Over 20,000 projected direct and indirect skilled jobs, building a South Asian fab engineering workforce
- Shorter lead times for Indian manufacturers, with indirect pricing effects on commodity ICs regionally
- A reference case that makes a second South Asian fab financeable
Frequently Asked Questions
Is Tata’s Dholera fab a TSMC plant?
No — it’s PSMC, not TSMC. Tata Electronics’ technology partner is Powerchip Semiconductor Manufacturing Corporation of Taiwan, which supplies fab design, construction support and engineering technology transfer. The confusion arises because both companies are Taiwanese foundries with 300mm operations. TSMC has no announced role in the Dholera project.
Who is PSMC and what does it actually make?
PSMC is a Taiwanese foundry specialising in mature process nodes and memory. Its business sits at 28nm and above, which is why Tata selected it for a first fab rather than a leading-edge partner. The product categories it supports include power management ICs, display driver ICs, microcontrollers and analogue or mixed-signal parts for industrial and automotive use.
How much does the Dholera fab cost and who is paying?
₹91,000 crore, roughly $11 billion. The Indian government provides 50% fiscal support on a pari-passu basis under a Fiscal Support Agreement signed in March 2025, so state funds release in step with Tata’s spending. As of November 2026, Tata Electronics is in early talks to raise up to $2 billion in bank debt, with a first tranche of up to $800 million.
When will the Dholera fab start commercial production?
Mid-2028, per India’s Technology Minister Ashwini Vaishnaw, revised from an earlier late-2026 target. First test chips are targeted around the end of 2026. The gap exists because tool qualification, metrology setup and yield learning follow construction and tool install rather than running in parallel with them.
Will Dholera make smartphone or AI chips?
Not flagship ones. Process nodes from 28nm to 110nm cannot produce modern smartphone SoCs or AI accelerators, which require 3nm and 2nm class processes. Dholera will instead make power management ICs, display drivers and microcontrollers — the supporting silicon that goes inside phones, vehicles, appliances and industrial equipment.
Does the Dholera fab affect chip prices in Pakistan?
Not directly, and not before 2028. Whether Indian output reaches Pakistani buyers depends on trade policy rather than installed capacity. The realistic effect is indirect: added regional mature-node supply softens global pricing for commodity ICs used in chargers, inverters and televisions, and it builds an engineering talent pool that employers across South Asia recruit from.
What is the difference between the Dholera fab and the Assam OSAT plant?
Dholera fabricates wafers; Assam packages and tests chips. The ₹27,000 crore Assam OSAT facility handles assembly and test. Because wafers are commercially useless until they are packaged, the two plants together form an end-to-end domestic chain rather than duplicate investments in the same step.
What Could Still Go Wrong — And What the Alternatives Are
The execution risks are documented in the project’s own revision history. The timeline has already moved from late 2026 to mid-2028, the node roadmap was revised downward before production began, and first-generation fab yield stays unproven until customers qualify parts against their own specifications. A further schedule adjustment is therefore the most sensible single outcome to plan around, because two revisions in eighteen months is the pattern the record shows rather than an anomaly.
The structural risks sit outside Tata’s direct control. Continuous power and ultrapure water supply at Dholera, dependency on ASML and other tool vendors for install and service response times, established mature-node capacity in China and Taiwan that can undercut a new entrant on price, and government disbursement keeping pace with capital spend all govern the outcome. Research from Oak Ridge National Laboratory on advanced manufacturing and semiconductor materials underlines how tightly utility stability, materials purity and skilled-operator availability constrain large-scale fabrication throughput.
For buyers, the practical guidance is unglamorous. Existing Taiwanese, Korean, Chinese and Japanese mature-node suppliers remain the default source through at least 2028, and regional assemblers should not rebuild sourcing plans around Dholera until test chips and customer qualifications are publicly confirmed. This article assesses public statements and reporting; it is not an engineering audit of the facility.
The Bottom Line
Tata’s Dholera fab is a PSMC project, and getting the partner right is what keeps expectations honest. The specification is settled: ₹91,000 crore, 50,000 wafer starts per month, 300mm wafers, nodes from 28nm to 110nm, with production opening on 90nm and 55nm. Because the output is mature-node workhorse silicon rather than leading-edge logic, the payoff for the region is supply resilience, a packaging route through Assam and an engineering workforce — not a domestically fabricated flagship processor. Two milestones are worth tracking and nothing else: test chips around the end of 2026, then commercial operations in mid-2028.
Read more from The Verge PK’s technology coverage.
References
- Tata Electronics — project and partnership announcements
- Press Information Bureau, Government of India — India Semiconductor Mission approvals and Fiscal Support Agreement
- ASML — Tata Electronics partnership announcement, May 2026
- TrendForce — foundry node and capacity analysis
- The Economic Times — Tata Electronics $2 billion loan discussions, November 2026
- National Institute of Standards and Technology — semiconductor metrology and CHIPS R&D programmes
- U.S. Patent and Trademark Office — technology transfer and IP in manufacturing partnerships
- Oak Ridge National Laboratory — advanced manufacturing and semiconductor materials research